Connect with us

Gorontalo Utara

What Does Impairment Mean in Accounting?

Published

on

Asset accounts that are likely to become impaired are the company’s accounts receivable, goodwill, and fixed assets. IFRS implements a one-step approach to identify and report impaired assets. An impairment loss occurs when the carrying amount of an asset is greater than its recoverable amount.

  1. The total write-off is usually spread across the complete life of the asset, also considering its expected resale value.
  2. The depreciation (amortisation) charge is adjusted in future periods to allocate the asset’s revised carrying amount over its remaining useful life.
  3. Therefore, IAS 36 requires companies to record the impairment whenever it occurs.
  4. The table above shows that as of 31 December 20X1, the 12-month ECL amount to $2,224, while the lifetime ECL total $6,722.
  5. The illustrative calculation of the loss rate for B2C customers is presented below.

If its fair market value is less than the carrying value, you will need to record an impairment loss for the difference. Under GAAP rules, the total dollar value of an impairment is the difference between the asset’s carrying value and its fair market value. Under International https://adprun.net/ Financial Reporting Standards (IFRS), the total dollar value of an impairment is the difference between the asset’s carrying value and the recoverable value of the item. The recoverable value can be either its fair market value if you were to sell it today or its value in use.

Things that cause impairment internally include physical damage to the asset, causing a reduction in its value. A debit entry is made to “Loss from Impairment,” which will appear on the income statement as a reduction of net income, in the amount of $50,000 ($150,000 book value – $100,000 calculated fair value). After assessing the damages, ABC Company determines the building is now only worth $100,000. The building is therefore impaired and the asset value must be written down to prevent overstatement on the balance sheet.

The second step measures the impairment loss after passing the step one test. The write-down amount is equal to the difference between the asset book value and fair value (or the sum of discounted future cash flows if the fair value is unknown). Assets are tested for impairment on a periodic basis to ensure the company’s total asset value is not overstated on the balance sheet. According to generally accepted accounting principles (GAAP), certain assets, such as goodwill, should be tested on an annual basis.

Impaired Asset

And companies are not required to disclose what is determined to be the fair value of goodwill, even though this information would help investors make a more informed investment decision. Impairment charges came into the spotlight again during the Great Recession. Weakness in the economy and the faltering stock market forced more goodwill charge-offs and increased concerns about corporate balance sheets. This article will define the impairment charge and look at its good, bad, and ugly effects. Similarly, while the standard shows how to recognize impairment losses, it does not give detailed information about companies’ processes. ABC Co. has total assets worth $1 million after calculating the carrying value at the end of the accounting period.

Under the U.S. generally accepted accounting principles, or GAAP, assets that are considered “impaired” must be recognized as a loss on an income statement. But at every accounting period reporting date you’re expected to test each asset for impairment and declare them as ‘impaired’ if necessary. If the market value of an asset is lower than the carrying value, the asset is impaired and must be reduced to its fair market value, and the amount of the write-down will be reported as a loss. This often occurs when the asset is depreciated or amortized at an underestimated amount or following a decline in the asset’s market value.

If there is impairment, then the difference between the fair value of the asset and its carrying amount is written off. This write-off occurs at once; the charge is not spread over multiple accounting periods. Generally, amortization is believed to be a systematic decrease in an intangible asset’s book value, based on the planned amortization plan. The total write-off is usually spread across the complete life of the asset, also considering its expected resale value. If the asset’s carrying value exceeds the recoverable amount, then the company must recognize an impairment loss.

This impairment test may have a substantial financial impact on the income statement, as it will be charged directly as an expense on the income statement. In some cases, goodwill may be completely written off and removed from the balance sheet. Consequently, Entity A recognises a total interest income of $235,654 and credit losses amounting to $735,654, resulting in a net loss of $500,000. This is due to 12-month ECL being weighted by the probability of default (PD).

Impairment occurs when assets are sold or abandoned because the company no longer expects them to benefit long-run operations. The asset’s value is then ‘written down’ to the new, lower impairment accounting definition recoverable amount as an ‘impairment loss’. This is recorded as an expense on your income statement and the decreased value of the asset is now on your overall balance sheet.

Impairment vs. depreciation and amortization

However, on 1 January 20X2, Entity B’s financial situation significantly deteriorated, leading Entity A to classify its loan to Entity B as credit-impaired (stage 3). Entity A anticipated receiving only $0.5 million on 31 December 20X4 (same repayment date). Therefore, the expected credit loss at the repayment date is $1 million, which when discounted using the original EIR of 10.7%, equates to a present value of $737,788 as of 1 January 20X2. The process of calculating interest income on credit-impaired financial assets is discussed in a separate section.

Cash flows in ECL measurement

Among these, ABC Co. has a vehicle with a carrying value of $100,000, which has suffered physical damage. All these assets have a specific standard that addresses how companies should deal with impairment for them. Other than these, the impairment of assets applies to all other assets within a company. Furthermore, if an asset’s fair value reduces in the market, it may also cause impairment to it.

An impairment loss should only be recorded if the anticipated future cash flows are unrecoverable. When an impaired asset’s carrying value is written down to market value, the loss is recognized on the company’s income statement in the same accounting period. An asset is impaired if its projected future cash flows are less than its current carrying value. Another indicator of potential impairment occurs when an asset is more likely than not to be disposed prior to its original estimated disposal date.

Although IFRS 9 doesn’t explicitly prescribe how to measure the proceeds from collateral, the fair value appears to be the most logical option. The table above shows that as of 31 December 20X1, the 12-month ECL amount to $2,224, while the lifetime ECL total $6,722. Impairment comes from either a sudden, one-off cause that results in a quick, dramatic fall in the asset’s value, or a quick sequence of related events.

Even professionals can come to different conclusions about the same asset. Depreciation and impairment often get muddled because they both govern an asset’s decrease in value. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided. Understand what impairment is, how it differs from depreciation and amortization, and how to calculate and report it. Natalya Yashina is a CPA, DASM with over 12 years of experience in accounting including public accounting, financial reporting, and accounting policies. Over 1.8 million professionals use CFI to learn accounting, financial analysis, modeling and more.

Initial recognition of financial assets following a drawdown on a loan commitment

This amount was payable on 31 December each year until the bond’s maturity date on 31 December 20X6. However, Entity X experienced financial difficulties in 20X2 and failed to pay the coupon due on 31 December 20X2. Believing that Entity X would be capable of partial repayment of the face value at the redemption date, Entity A purchased the bond for $5,000 on 1 January 20X3.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Gorontalo Utara

Menjaga Tanggomo Agar Tak Lekang: Ikhtiar Kemenbud RI dan Elnino Mohi Menyapa Sekolah lewat program Semarak Budaya 2026
Published

on

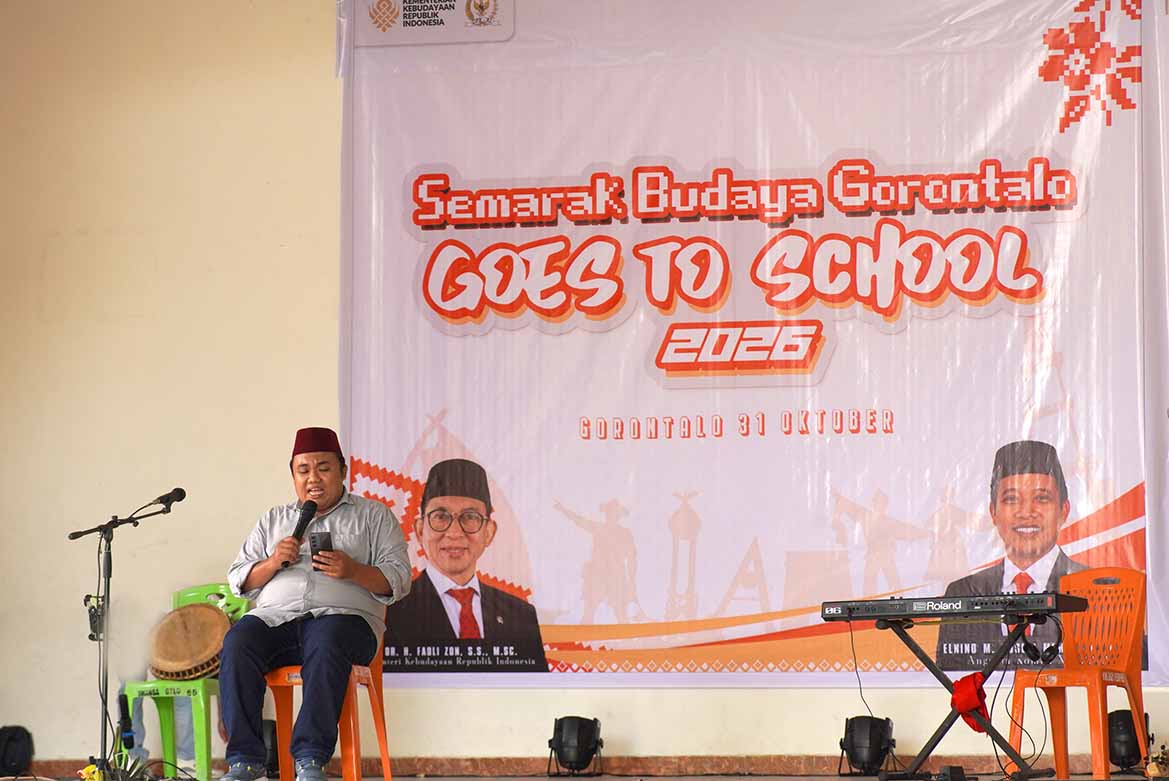
Alunan bambu Polopalo berpadu dengan petikan ritmis Gambusi terdengar bergema di Aula SMA Negeri 1 Gorontalo, Sabtu (31/10/2026). Di tengah suasana yang hangat itu, ratusan mata siswa terpaku saat bait-bait syair Tanggomo mulai dilantunkan. Sastra tutur lisan yang sarat akan petuah leluhur dan riwayat sejarah Gorontalo tersebut dihadirkan tanpa sekat jarak, disusul keanggunan gerak tari adat yang memikat pandangan para remaja yang memadati ruangan.

Hari itu, program Semarak Budaya Gorontalo 2026 bertajuk “Goes to School” hadir membawa warna berbeda di lingkungan satuan pendidikan formal. Kegiatan ini merupakan inisiatif kolaboratif antara Kementerian Kebudayaan Republik Indonesia dengan legislator Komisi X DPR RI asal Gorontalo, Elnino M. Husein Mohi. Tujuannya sederhana namun mendasar: menyalakan kembali api kecintaan terhadap warisan budaya lokal langsung di bilik-bilik pendidikan.

Hadir mewakili Elnino M. Husein Mohi, Tenaga Ahli Komisi X DPR RI, N. Syamsu Panna, S.Kom, menyampaikan pesan yang menyentuh ruang emosional para peserta. Dalam pandangannya, menjaga tradisi bukanlah upaya menolak kemajuan zaman, melainkan meneguhkan identitas diri anak muda di tengah pusaran arus global.

“Langkah ini kami hadirkan tidak lain dan tidak bukan semata untuk terus menggali serta menumbuhkan perasaan cinta yang tulus terhadap kebudayaan daerah sendiri. Kita ingin para generasi penerus di Gorontalo tidak hanya bangga pada budaya asing, tetapi justru tegak kepalanya karena memiliki warisan tradisi yang begitu adiluhung,” tutur Syamsu Panna saat menyampaikan sambutan.

Dukungan nyata terpancar dari jajaran pemerintah daerah. Kepala Bidang PSMA dan Diksus Dinas Pendidikan dan Kebudayaan Provinsi Gorontalo, Agus Sumba, yang hadir di lokasi, mengungkapkan kebanggaannya melihat antusiasme para siswa dan guru. Ia memandang pertemuan langsung antara pelajar dengan maestro tradisi sebagai medium edukasi karakter yang paling hidup.

“Pendidikan yang baik adalah pendidikan yang berakar pada kearifannya sendiri. Kami menyambut positif kemitraan erat antara Komisi X DPR RI dan Kementerian Kebudayaan ini. Ini ruang belajar yang autentik bagi pembentukan karakter anak didik kita,” kata Agus Sumba.

Hal ini dijawab melalui sesi workshop interaktif produksi konten promosi kebudayaan yang diikuti sekitar 100 peserta dari kalangan siswa dan guru. Para peserta diajak membedah teknik pengambilan gambar menggunakan kamera ponsel pintar, penyusunan narasi (storytelling), penyuntingan video pendek, hingga strategi distribusi konten kebudayaan di platform digital populer seperti Instagram Reels, TikTok, dan YouTube.

Melalui bekal teknis tersebut, para siswa SMAN 1 Gorontalo diharapkan tidak hanya berperan sebagai konsumen hiburan digital, melainkan bertransformasi menjadi duta budaya muda yang aktif mempromosikan pesona dan nilai luhur Gorontalo ke ruang publik digital nasional maupun global.

Continue Reading

Gorontalo Utara

Sinergi TNI-Polri Jaga Kondusivitas! Polsek Sumalata dan Batalion TP 824 Moea Gelar Patroli Gabungan
Published

on

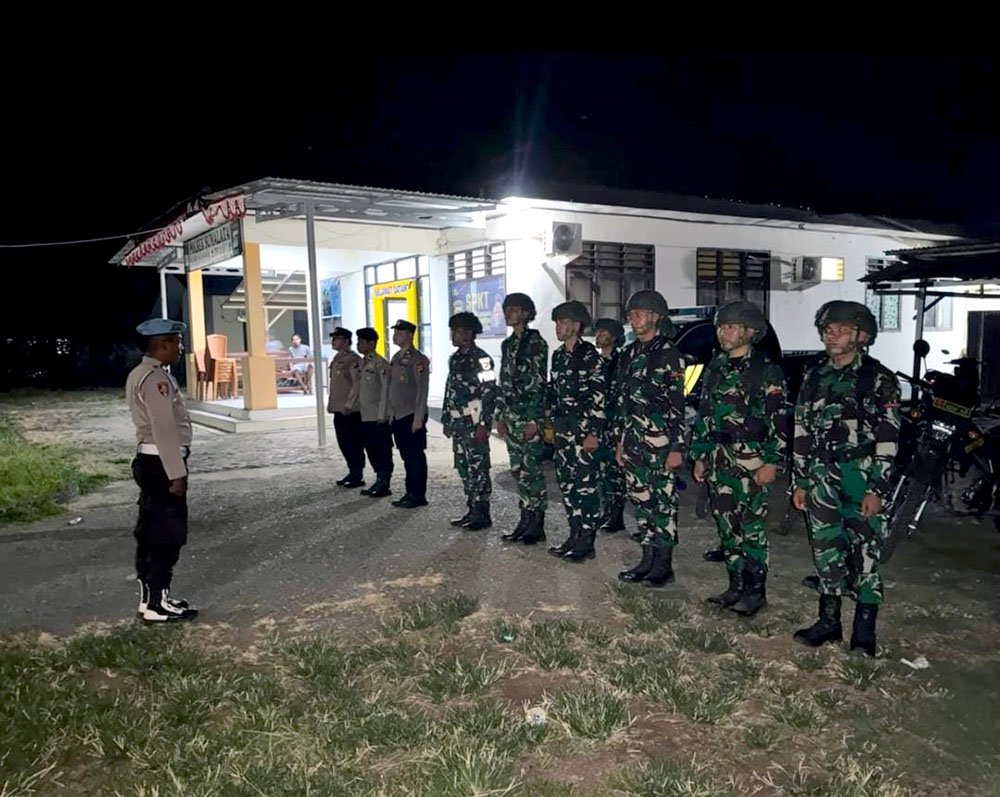
GORUT – Dalam upaya mengantisipasi serta mencegah potensi gangguan keamanan dan ketertiban masyarakat (kamtibmas), jajaran Polsek Sumalata bersama personel Batalion TP 824 Moea menggelar aksi patroli gabungan Kegiatan Rutin Yang Ditingkatkan (KRYD) di wilayah hukum Polsek Sumalata, Kamis (15/10/2026) malam.

Patroli presisi yang dimulai sejak pukul 20.00 WITA tersebut mengikutsertakan personel piket Regu II dan Kanit Provos Polsek Sumalata yang berkolaborasi erat dengan personel Batalion TP 824 Moea. Agenda ini difokuskan pada langkah pencegahan tindak kriminalitas serta menjaga situasi keamanan wilayah agar tetap kondusif.

Kapolsek Sumalata, IPTU Medin Pakaya, S.H., menjelaskan bahwa patroli gabungan ini merupakan wujud sinergitas TNI-Polri sekaligus langkah preventif untuk mengantisipasi potensi kerawanan kamtibmas di tengah kehidupan masyarakat.
Dalam pelaksanaannya, personel gabungan menyisir sejumlah lokasi keramaian yang kerap menjadi tempat berkumpulnya warga, serta titik-titik strategis yang dinilai rawan terjadi gangguan keamanan dan ketertiban.

Selain melangsungkan pemantauan situasi di lapangan, petugas juga menyapa warga dan memberikan imbauan kamtibmas secara persuasif agar masyarakat turut berperan aktif menjaga keamanan di lingkungan masing-masing.

Kehadiran personel TNI dan Polri secara langsung di lapangan diharapkan mampu meningkatkan rasa aman bagi masyarakat sekaligus mempersempit ruang gerak serta celah terjadinya aksi kriminalitas.

IPTU Medin Pakaya menegaskan, pelaksanaan KRYD ini menjadi komitmen berkelanjutan kepolisian dalam menekan angka kejahatan serta mengantisipasi dinamika gangguan keamanan, khususnya di seluruh wilayah hukum Polsek Sumalata.

Aksi patroli gabungan tersebut berlangsung hingga pukul 22.05 WITA. Selama kegiatan penjelajahan wilayah dilaksanakan, situasi kamtibmas di wilayah hukum Polsek Sumalata terpantau aman, lancar, dan terkendali.

Polsek Sumalata memastikan akan terus mengedepankan tindakan pencegahan melalui patroli berkala, serta merangkul seluruh elemen masyarakat untuk bersama-sama merawat situasi kamtibmas yang aman, harmonis, dan tertib.
Continue Reading

Daerah

Respon Dampak Buruk El nino! Laskar Gerindra Gorut Langsung Gerak Cepat

Published

on

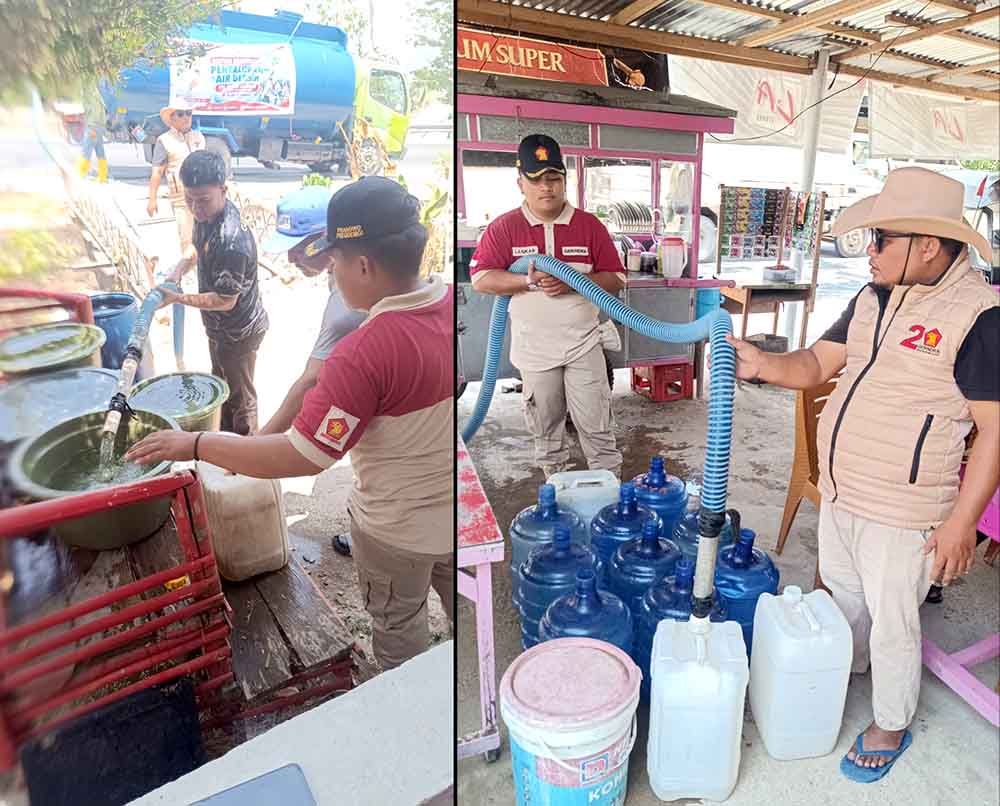
GORONTALO UTARA — Usai merampungkan agenda Pendidikan dan Pelatihan (Diklat) beberapa hari lalu, Laskar Gerindra Gorontalo Utara (Gorut) langsung diterjunkan ke lapangan untuk melayani masyarakat. Melalui instruksi Dewan Pimpinan Cabang (DPC) Partai Gerindra Gorontalo Utara, para kader menyalurkan bantuan air bersih ke sejumlah desa yang tengah dilanda kekeringan ekstrem di Kecamatan Kwandang.

Aksi sosial ini menyasar wilayah yang terdampak krisis pasokan air bersih, dimulai dari Desa Ombulodata dan Desa Pontolo Atas. Penyaluran bantuan air bersih ini dipastikan akan terus berlanjut secara bertahap ke desa-desa lain yang membutuhkan di seluruh wilayah Kecamatan Kwandang.

Koordinator Laskar Gerindra Gorontalo Utara, Febriyan Mohu, menegaskan bahwa aksi tanggap darurat ini merupakan bentuk pengabdian nyata para kader pasca-pelatihan.

“Laskar Gerindra tidak hanya dididik untuk memiliki kedisiplinan internal, tetapi juga diajarkan untuk peka dan hadir di tengah kesulitan rakyat. Begitu selesai mengikuti pendidikan dan pelatihan, kami langsung bergerak ke lapangan menyalurkan air bersih bagi warga yang mengalami krisis air. Langkah awal kami mulai dari Desa Ombulodata dan Desa Pontolo Atas, dan akan terus berlanjut ke desa-desa lain se-Kecamatan Kwandang yang membutuhkan,” tegas Febriyan Mohu.

Krisis air bersih yang melanda wilayah Gorontalo Utara tidak terlepas dari fenomena iklim El Niño Godzilla—sebuah fenomena pemanasan suhu permukaan laut tingkat kuat yang memicu musim kemarau ekstrem. Dampak fenomena ini menyebabkan penipisan cadangan air tanah, mengeringnya sumber-sumber air bersih warga, serta lumpuhnya pasokan air bersih di berbagai kawasan pemukiman.

Di tengah kondisi darurat pasokan air akibat fenomena cuaca ekstrem tersebut, Laskar Gerindra Gorut berkomitmen untuk terus siaga memfasilitasi kebutuhan mendasar masyarakat hingga pasokan air warga kembali normal.

Continue Reading

Facebook

Terpopuler